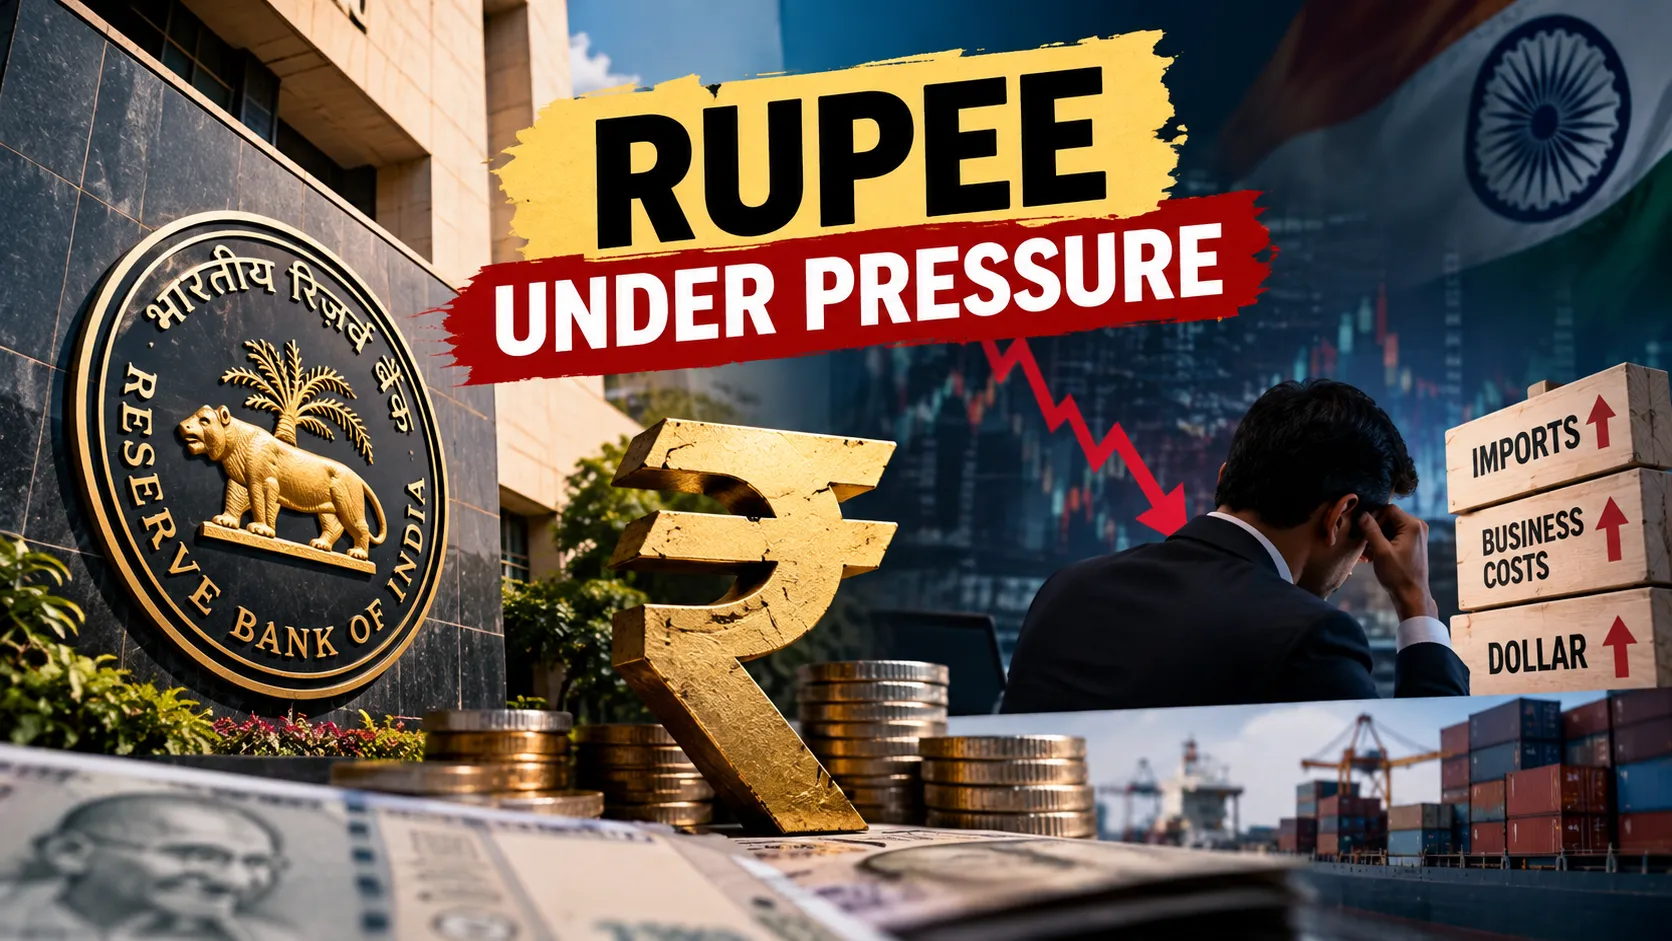
India has taken new steps to support the rupee as the currency faces pressure from high oil prices and money moving out of the country. However, the latest rules from the Reserve Bank of India have created confusion among banks. According to Reuters, several major lenders temporarily stopped giving quotes for dollar and rupee forward contracts while they tried to understand how the new requirements should apply.
The RBI has expanded a rule that requires banks to keep a cash reserve equal to 20 percent of certain foreign exchange contracts. The requirement now also covers contracts banks use to manage currency risks linked to their own assets and liabilities. The central bank has also restricted some foreign exchange contracts for overseas clients to genuine hedging needs instead of speculation. These steps aim to reduce pressure on the rupee.
The changes could also affect Indian businesses that need dollars for imports and international payments. Companies often use forward contracts to protect themselves against sudden currency movements. If these contracts become more expensive or harder to access, businesses may face higher costs or greater uncertainty while planning payments. However, the final impact will depend on how banks apply the rules and whether the RBI provides further clarification.
The rupee gained against the US dollar after the RBI announced its measures, but one day of improvement does not guarantee a lasting recovery. Global oil prices, foreign investment flows and demand for dollars will continue to influence the currency. The RBI now faces the challenge of supporting the rupee while ensuring that genuine business transactions can continue smoothly. The coming days will show whether the new measures achieve both goals.